All Categories
Featured
Navigating the 2026 Medicare Part D Enrollment Period
Table of Contents
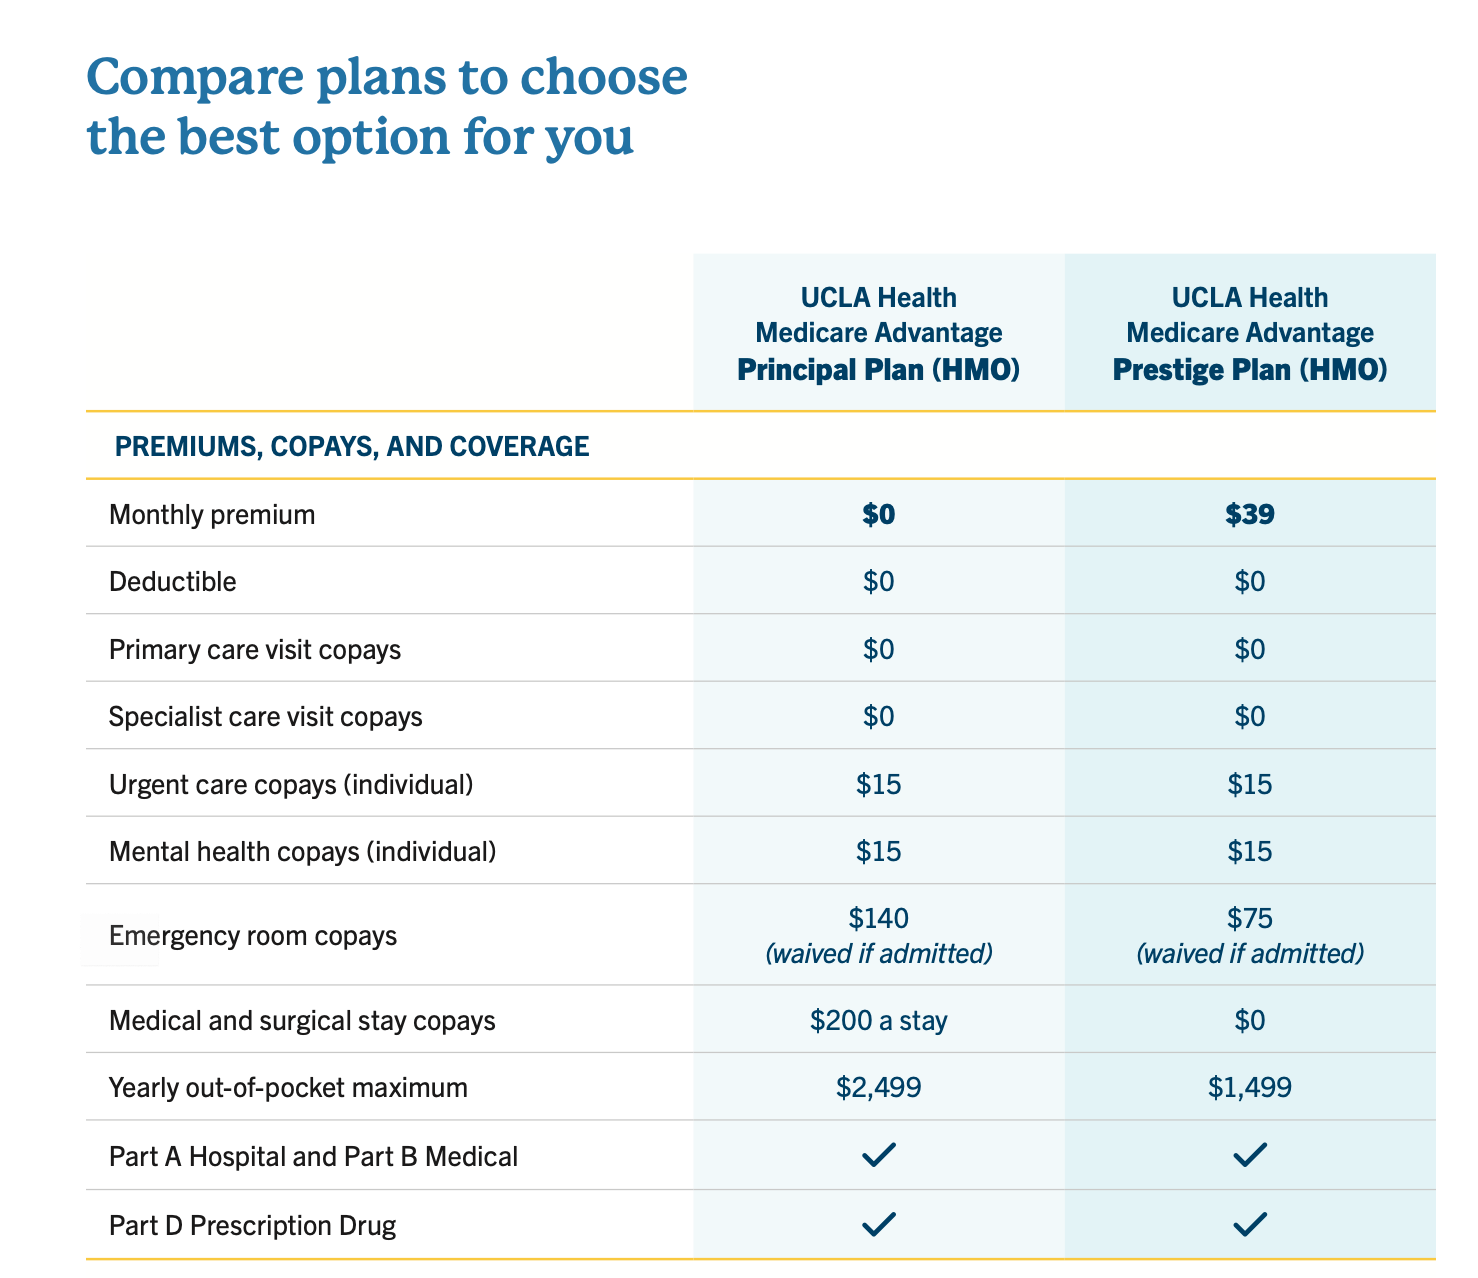
eligibility for financial help monthly premiums covered physicians estimated overall healthcare expenses for the year. When comparing expenses, consider your total health care expenses, not simply the regular monthly premium. Out-of-pocket expenses such as deductibles, co-payments, and co-insurance have a big impact on your total healthcare costs. When you discover the right prepare for you, you can apply.
If you've had particular changes in your life, you could certify for unique registration. These events can include: Job-related eventsLoss of coverageMarriage and divorceNew childMovingEarly retirementOther occasions
Thank You, Your message has been received. Technical Mistake, Please try again later on. Ask another question
Our objective is to provide all members with the highest quality healthcare with access to highly certified physicians. We hold ourselves liable for treating our members with self-respect and respect, supplying first-rate customer care, and acknowledging our dedication to the community as a regional corporation.
Explore our health insurance coverage prepares with protection for individuals under the age of 65. text Resume an application srtext Resume an individual or household insurance application icon lh-icon-- caret-right analytics-id.
Best Indexed Universal Life Benefits for Seniors
Health Insurance Coverage Guides There is no single health insurance strategy or provider that is "finest" for each Florida home. The best fit is the coverage that works with your doctors and hospitals, covers the prescriptions you require, gives you an acceptable balance of premium and out-of-pocket risk, and matches your eligibility, household, county, and enrollment timing.
If you are browsing for the, do not start with a provider name. Start with the things the strategy needs to do for you. suggests comparing more than the monthly premium. A useful plan comparison includes anticipated total annual expense, deductibles, copayments or coinsurance, the out-of-pocket maximum, service provider network, prescriptions, and the amount of care you expect to use.
Someone who anticipates regular professional care might put more weight on the deductible, copays, coinsurance, and maximum out-of-pocket direct exposure. A strategy is difficult to call "finest" if an important doctor, expert, healthcare facility, clinic, or health system is not in its network.
Provider networks can also work differently by plan type. Do not assume that 2 plans from the very same insurance company have the exact same network.
Finding Affordable 2026 Health Insurance for Your Family
Compare the premium together with the deductible, office-visit costs, coinsurance, prescription expenses, and annual out-of-pocket maximum. specifically recommends approximating total annual costs based upon just how much care your household expects to use. For a much deeper Florida-specific structure, see Affordable Medical insurance in Florida: How to Compare Overall Cost, Not Simply Premium.
A strategy that conserves a small amount each month can be the worse fit if it removes an important hospital system, puts a regular prescription at a much higher expense, or shifts significantly more risk to you when care is required. Marketplace plans are organized into Bronze, Silver, Gold, and Platinum classifications.
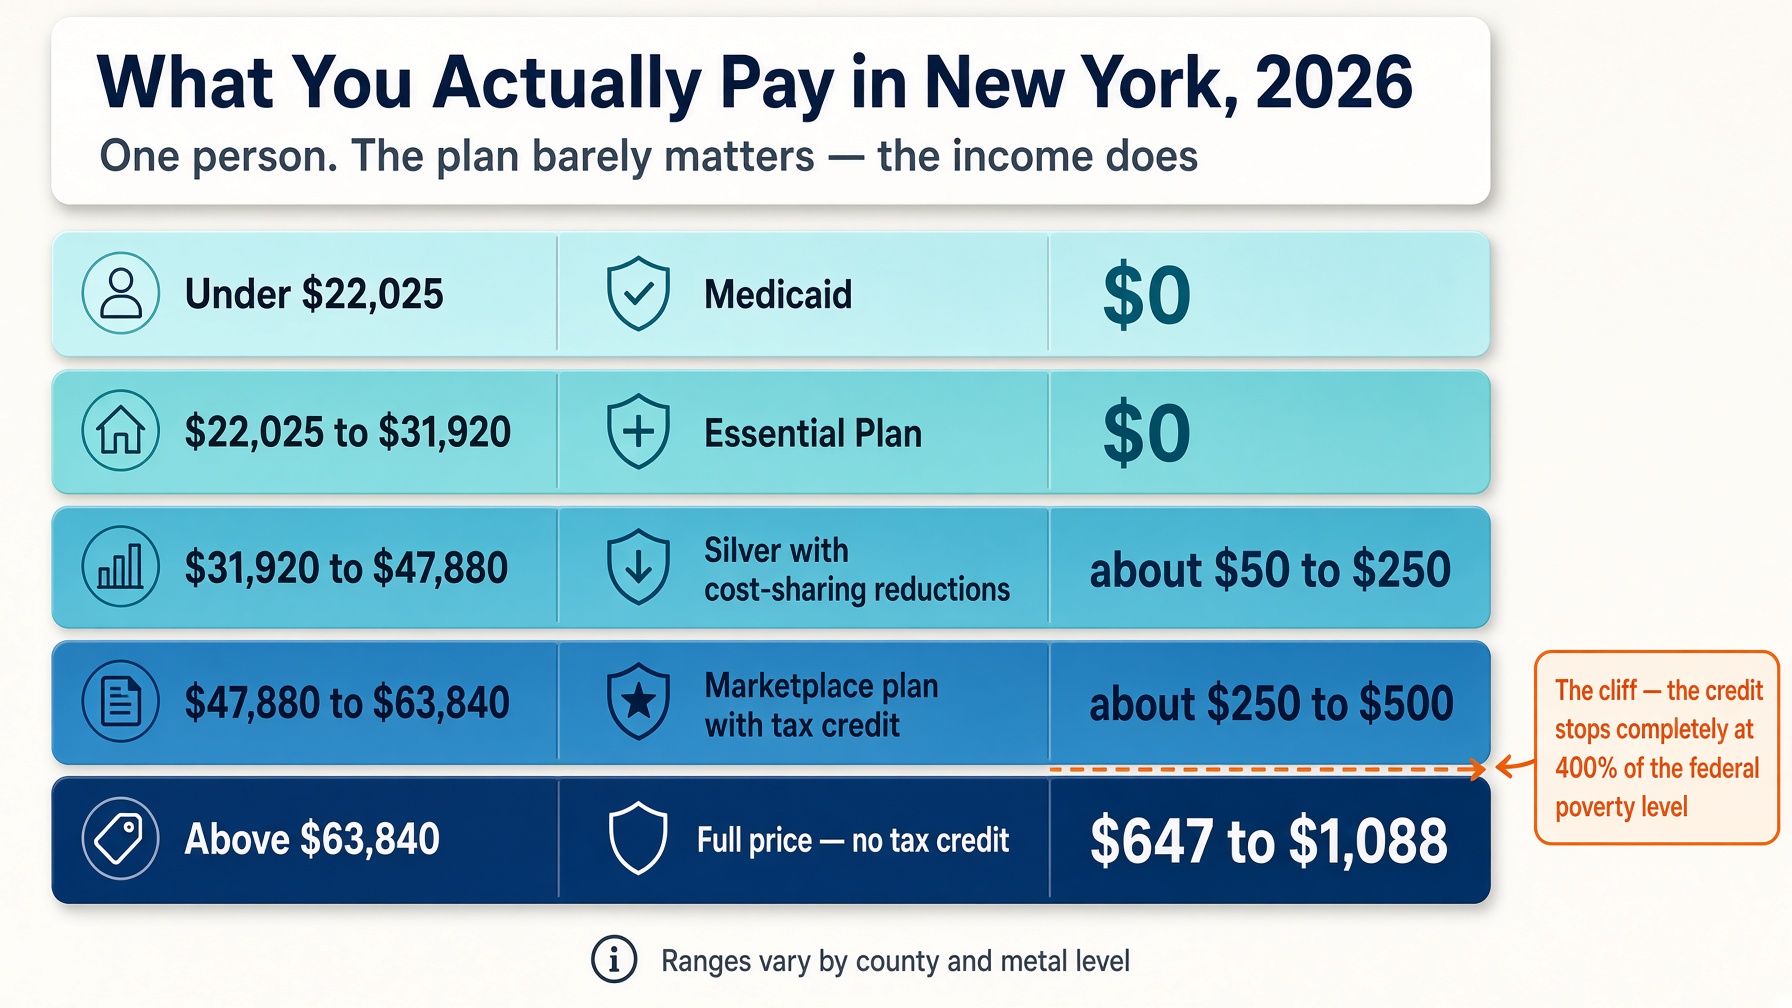
A Gold strategy is not automatically "better" than a Silver plan for every person, and a Bronze strategy is not automatically a bad strategy. If you qualify for cost-sharing decreases through the Marketplace, says those additional cost savings are available only with an eligible Silver strategy.
For qualified families, exceptional tax credits can decrease the monthly expense of Market protection. If you might certify for Market savings, compare the actual after-credit premium rather than comparing an unsubsidized Market cost with another alternative.
ACA-compliant plans bought through, where eligible households can access Market monetary help. ACA-compliant specific strategies purchased straight from an insurance company or through a representative outside Market premium tax credits do not apply to a strategy acquired outside the Marketplace. A different coverage classification that Florida Health Agents does not use as another name for off-Marketplace ACA protection.
Financial Stability Strategies Through Term Life Insurance
Florida's Department of Financial Services says 2026 ACA specific carriers might sell on the Marketplace, off the Exchange, or both, and directs customers to to see what is really available in their ZIP code. For a direct comparison of the 2 significant courses, checked out ACA vs. Private Health Insurance coverage in Florida and Private Health Insurance in Florida.

Latest Posts
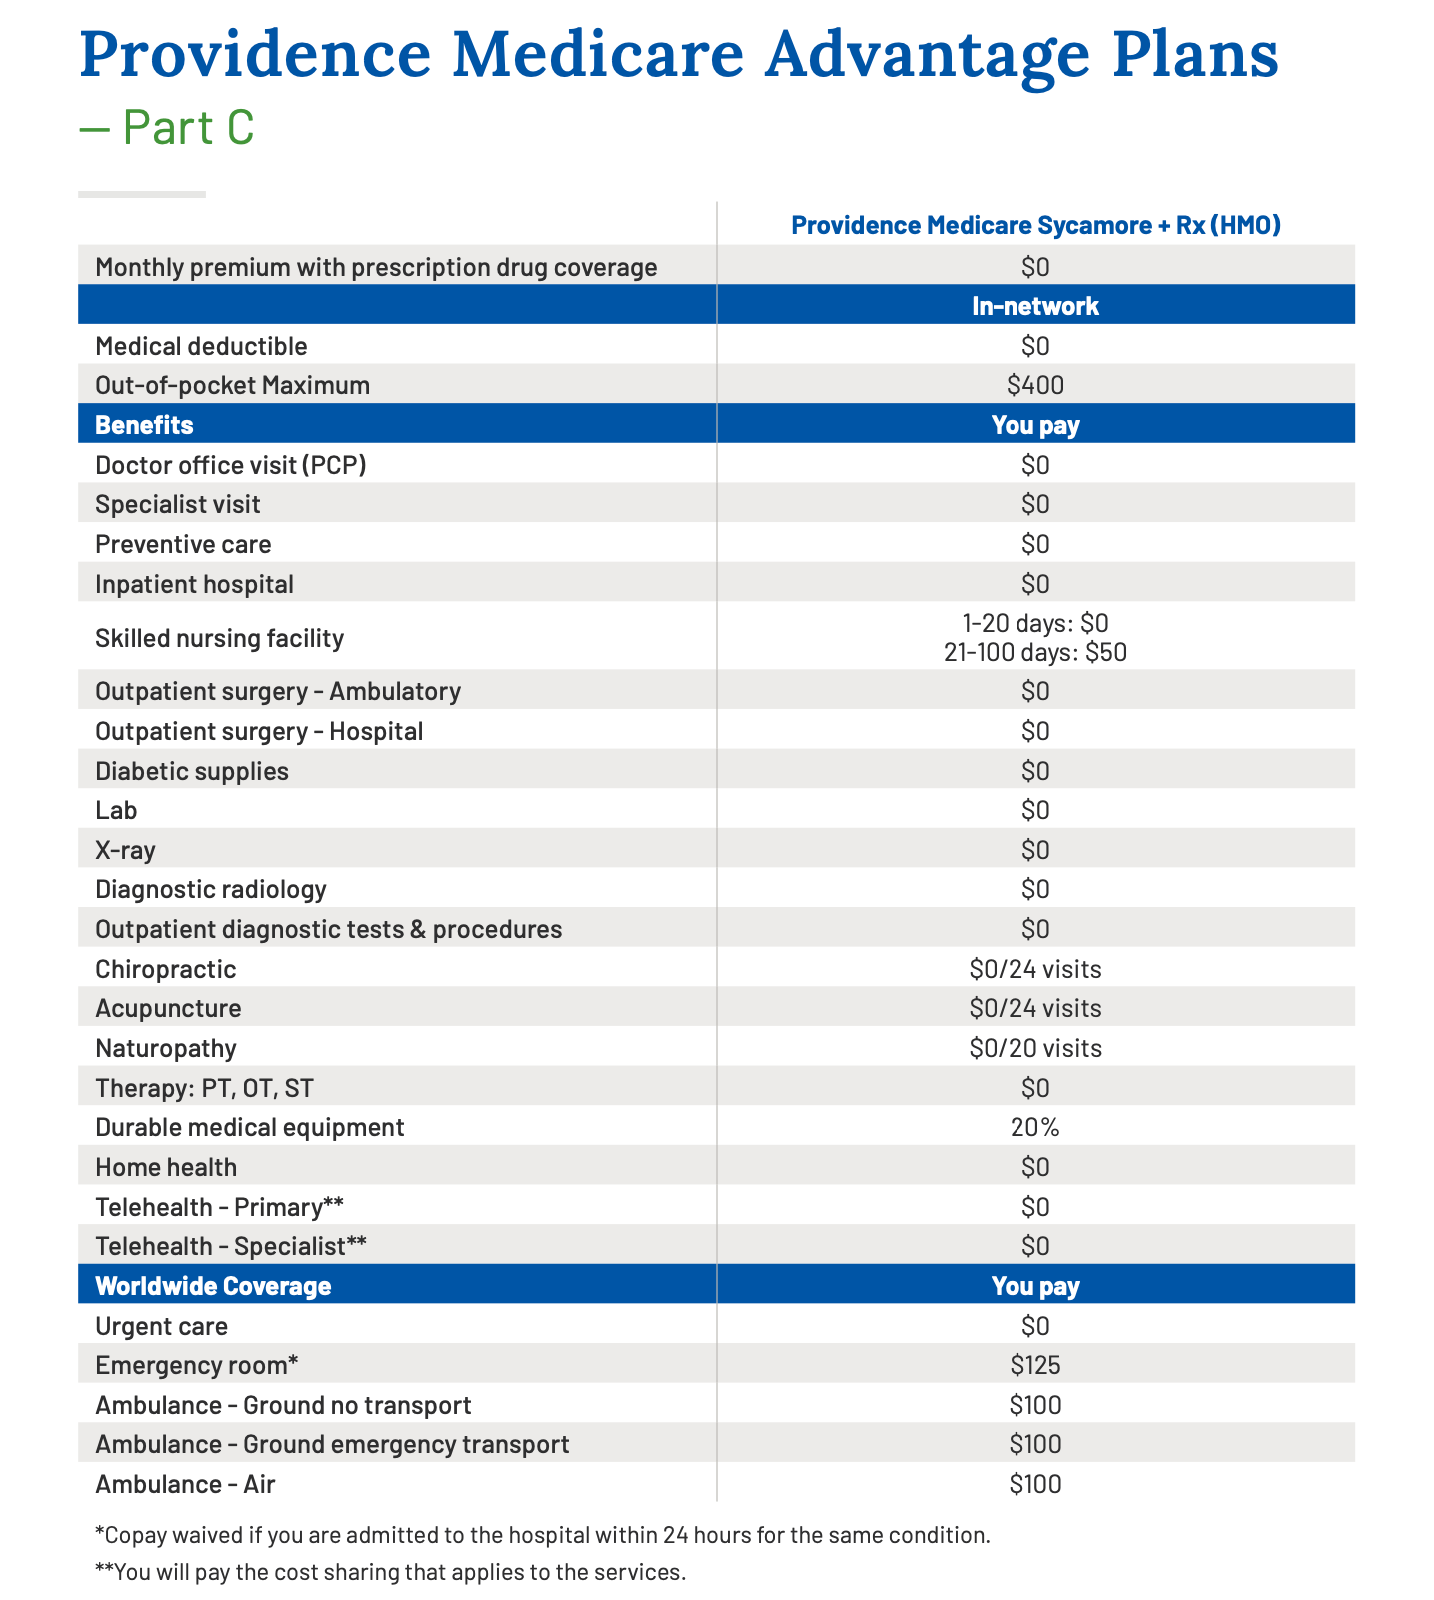
Evaluating PPO vs HMO Health Plans
Mechanics of Permanent Life Insurance to Protect Families
How to Evaluate Individual Health Insurance Costs