All Categories
Featured
How to Evaluate Individual Health Insurance Costs
Table of Contents
eligibility for monetary aid monthly premiums covered physicians approximated overall healthcare expenses for the year. When comparing expenses, consider your total healthcare costs, not simply the regular monthly premium. Out-of-pocket costs such as deductibles, co-payments, and co-insurance have a huge influence on your total healthcare costs. As soon as you find the ideal prepare for you, you can apply.

If you have actually had certain changes in your life, you might receive special enrollment. These occasions can consist of: Occupational eventsLoss of coverageMarriage and divorceNew childMovingEarly retirementOther events
Thank You, Your message has been gotten. Technical Error, Please try again later on. Ask another question
Our objective is to offer all members with the highest quality healthcare with access to highly certified physicians. We hold ourselves accountable for treating our members with dignity and respect, providing world-class customer care, and recognizing our dedication to the neighborhood as a local corporation.
Explore our medical insurance plans with coverage for individuals under the age of 65. text Resume an application srtext Resume a private or family insurance application icon lh-icon-- caret-right analytics-id.
Medicare in AnaheimLife Insurance Policies for Veterans
Health Insurance Guides There is no single health insurance coverage plan or provider that is "finest" for each Florida family. The finest fit is the coverage that works with your doctors and hospitals, covers the prescriptions you require, offers you an appropriate balance of premium and out-of-pocket threat, and matches your eligibility, family, county, and enrollment timing.
If you are searching for the, do not start with a provider name. Start with the things the strategy needs to do for you. suggests comparing more than the month-to-month premium. A useful strategy comparison includes anticipated overall yearly expense, deductibles, copayments or coinsurance, the out-of-pocket maximum, service provider network, prescriptions, and the amount of care you expect to utilize.
Someone who anticipates regular professional care might put more weight on the deductible, copays, coinsurance, and optimum out-of-pocket exposure. A plan is challenging to call "best" if an important physician, specialist, health center, center, or health system is not in its network.
Provider networks can likewise work in a different way by plan type. describes that HMOs, EPOs, PPOs, and other network structures can have different rules for out-of-network care, recommendations, and service provider access. Do not presume that 2 strategies from the exact same insurance provider have the very same network. If a company relationship is essential, validate involvement using the current plan directory site and, when possible, confirm with the service provider before registering.
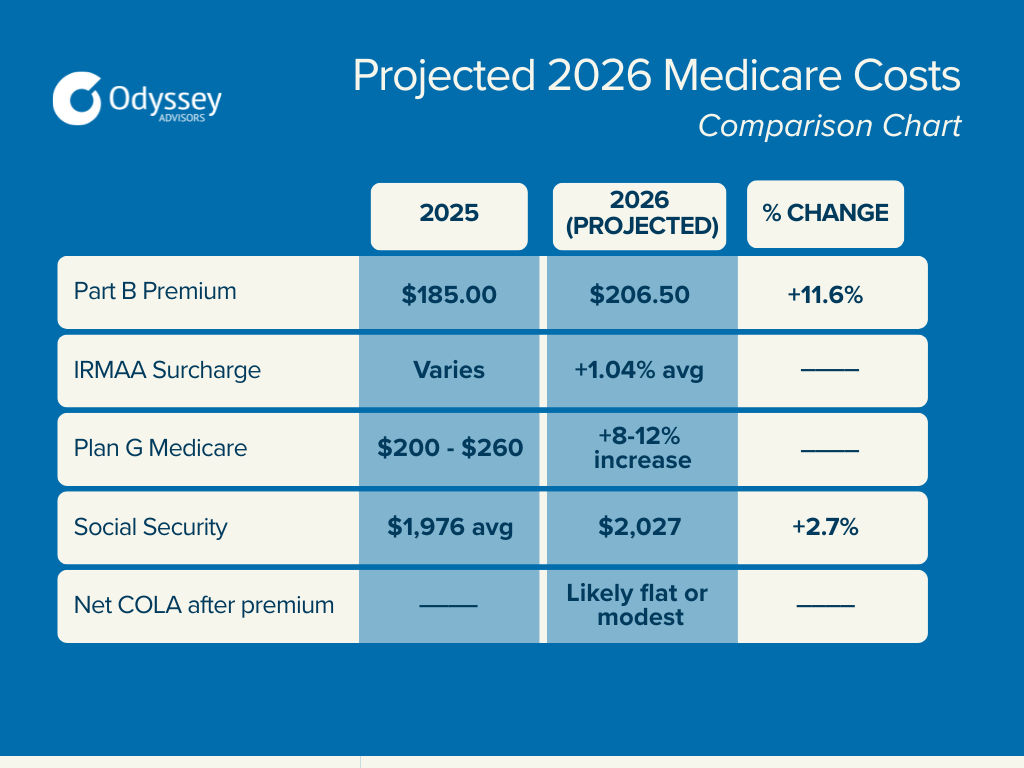
Navigating the 2026 Medicare Part D Enrollment Period
Compare the premium together with the deductible, office-visit expenses, coinsurance, prescription costs, and yearly out-of-pocket optimum. particularly advises estimating total annual expenses based on how much care your home anticipates to use. For a much deeper Florida-specific framework, see Affordable Medical insurance in Florida: How to Compare Overall Cost, Not Just Premium.
A strategy that conserves a percentage each month can be the worse fit if it removes an essential hospital system, puts a regular prescription at a much higher cost, or shifts substantially more risk to you when care is required. Marketplace plans are grouped into Bronze, Silver, Gold, and Platinum classifications.
That distinction matters. A Gold strategy is not immediately "much better" than a Silver prepare for everyone, and a Bronze strategy is not immediately a bad plan. Your anticipated usage of care, premium, deductible, out-of-pocket direct exposure, network, prescriptions, and offered cost savings all affect the choice. If you get approved for cost-sharing reductions through the Market, says those extra cost savings are offered just with an eligible Silver strategy.
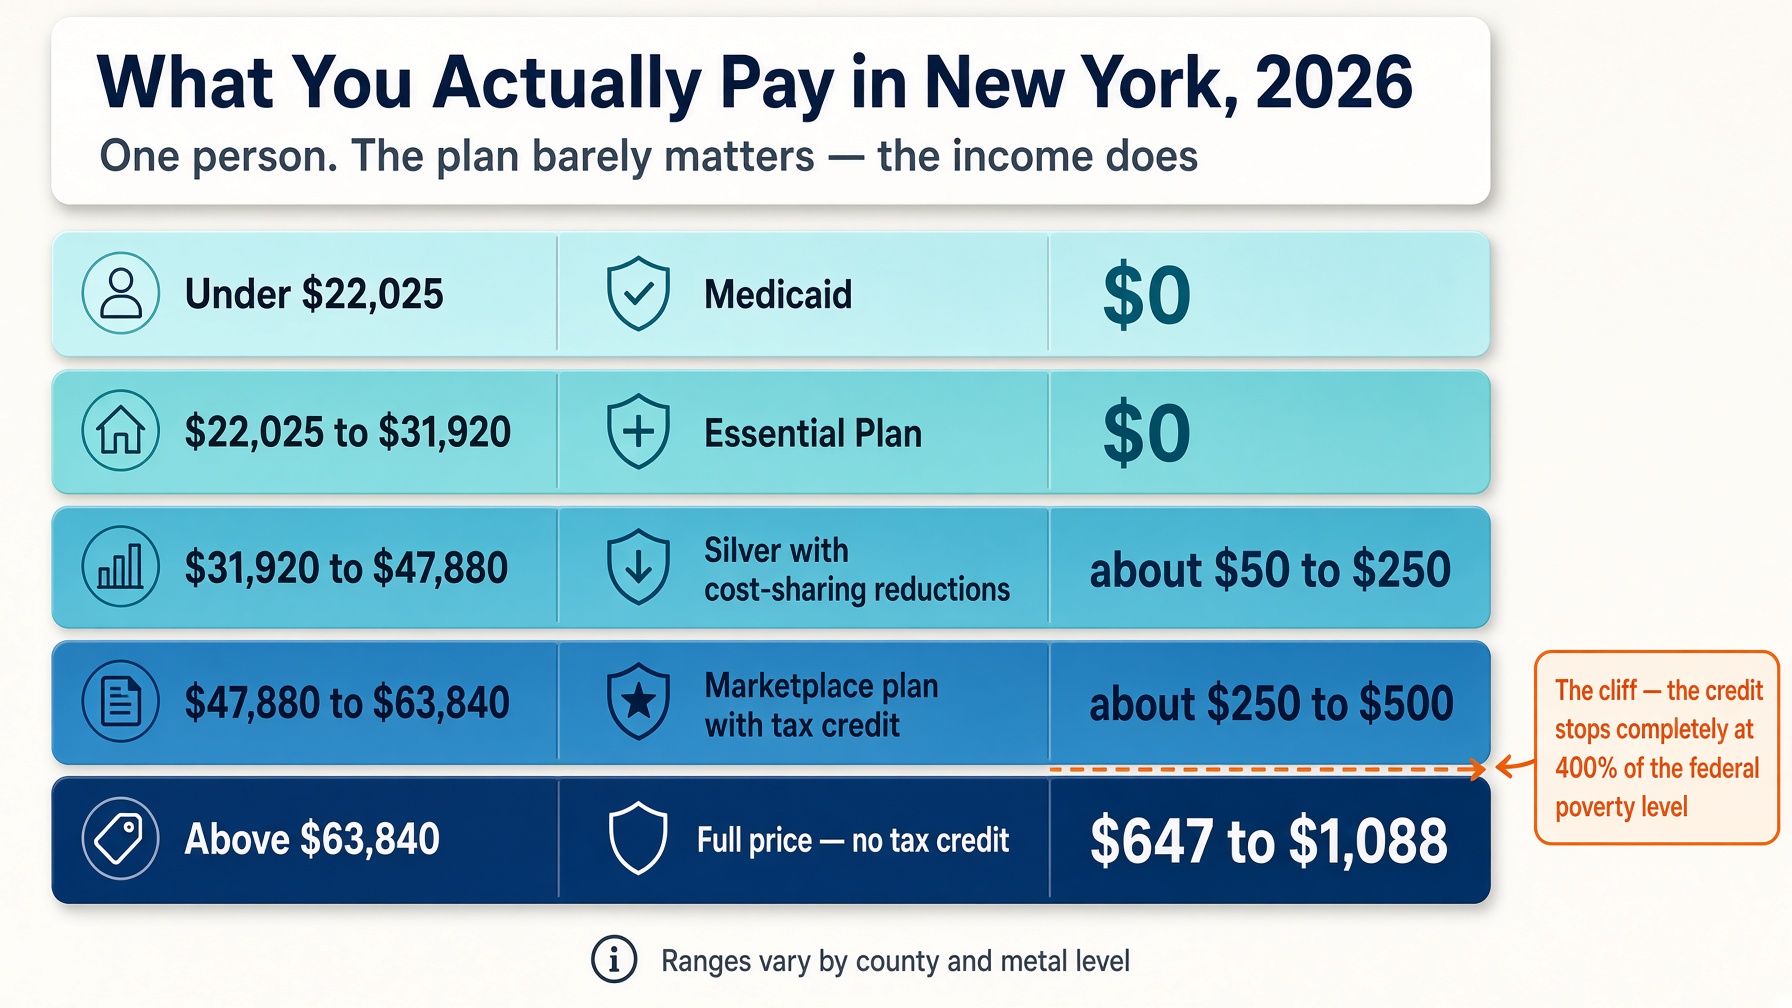
For eligible families, exceptional tax credits can decrease the month-to-month cost of Market protection. If you may qualify for Marketplace savings, compare the actual after-credit premium rather than comparing an unsubsidized Market cost with another alternative.
ACA-compliant plans purchased through, where eligible homes can access Marketplace monetary support. ACA-compliant individual plans bought straight from an insurer or through a representative outside Marketplace premium tax credits do not apply to a strategy bought outside the Marketplace. A separate coverage classification that Florida Health Agents does not use as another name for off-Marketplace ACA coverage.
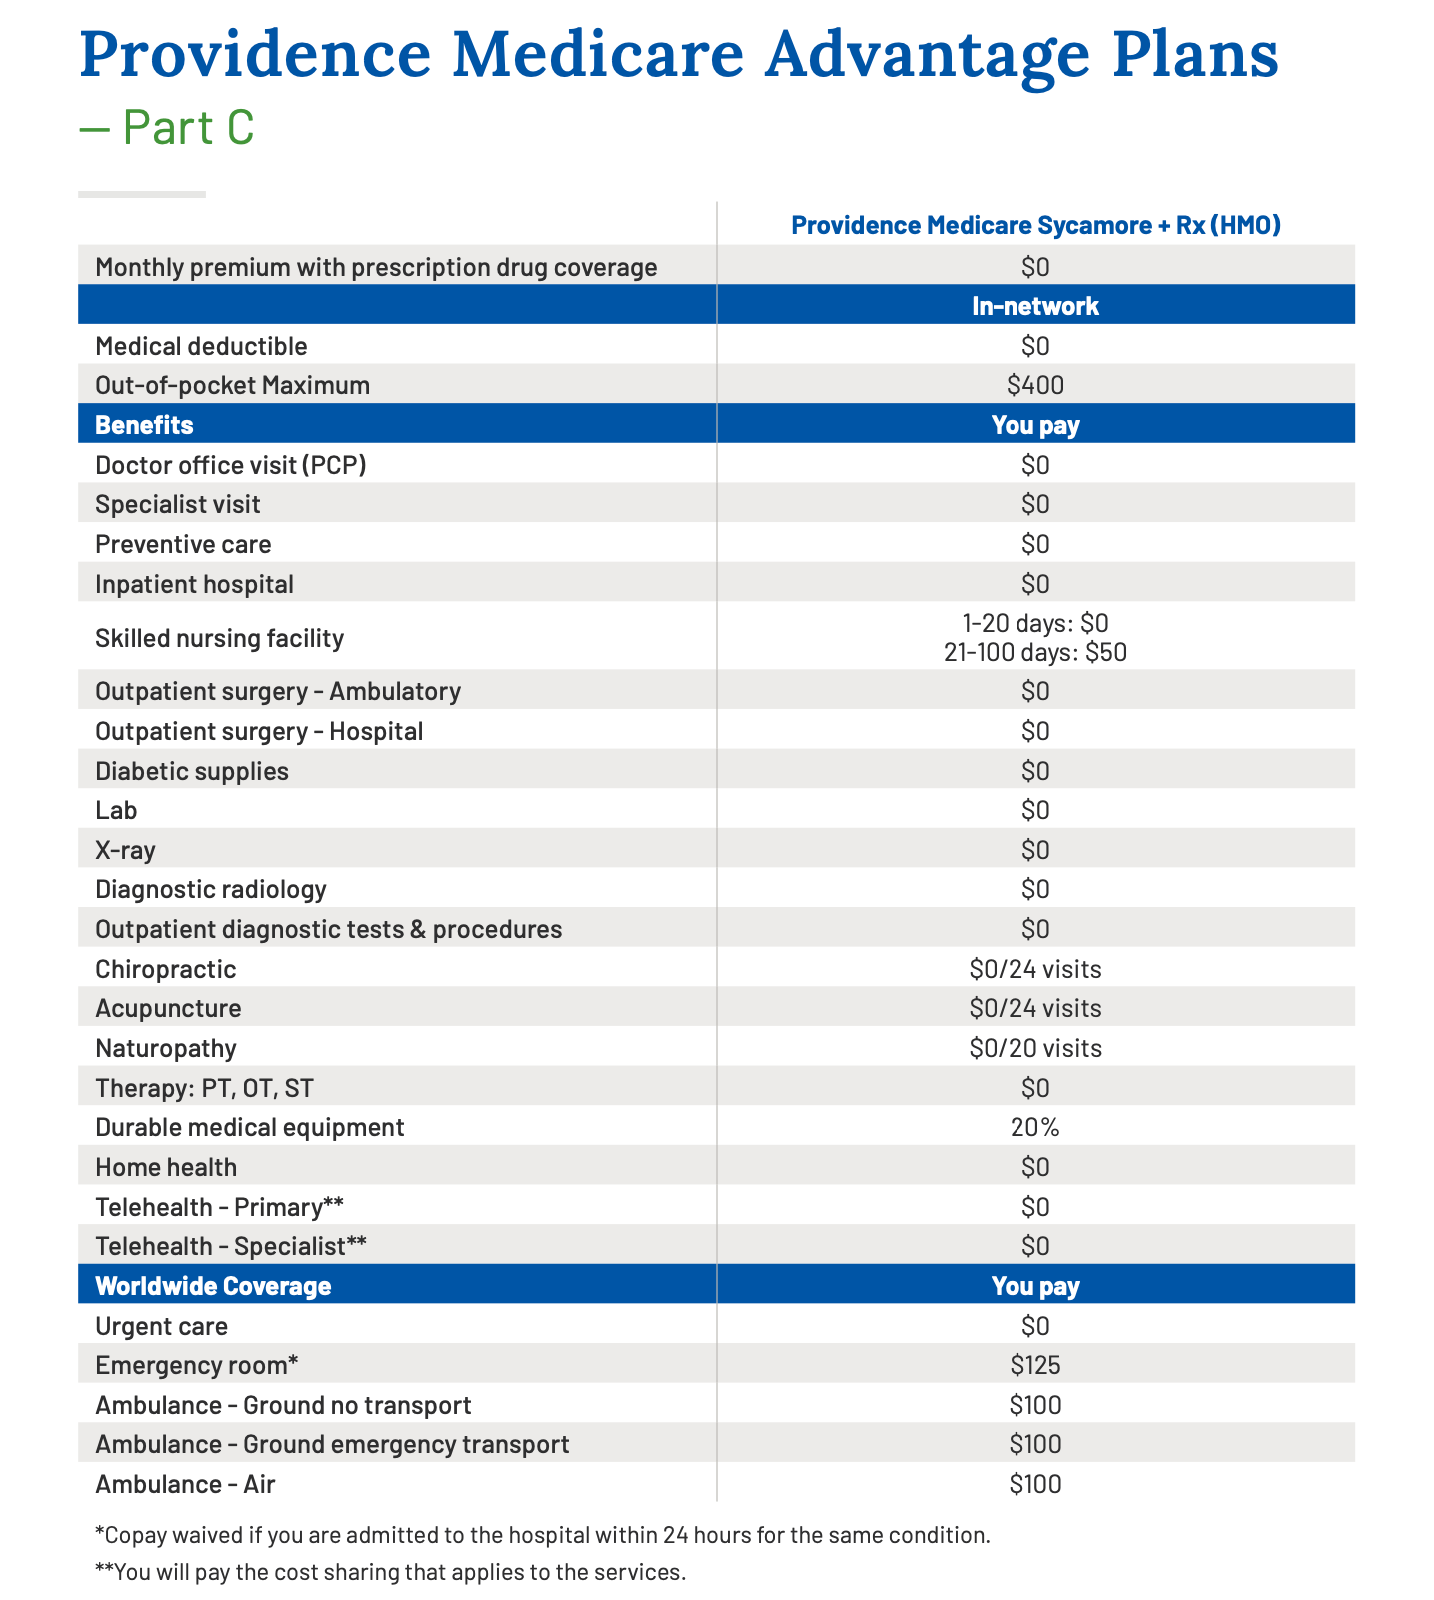
Choosing Your Best 2026 Medicare Supplement Coverage
Florida's Department of Financial Provider says 2026 ACA private carriers might offer on the Marketplace, off the Exchange, or both, and directs consumers to to see what is really readily available in their ZIP code. For a direct contrast of the 2 major paths, read ACA vs. Private Health Insurance coverage in Florida and Private Health Insurance Coverage in Florida.

Latest Posts
Evaluating PPO vs HMO Health Plans
Mechanics of Permanent Life Insurance to Protect Families
How to Evaluate Individual Health Insurance Costs